
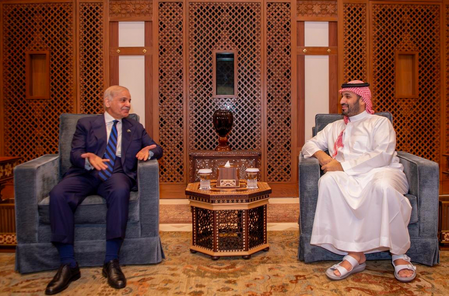
New Delhi, Nov 12 (IANS) Saudi Arabia has been bailing out cash-starved Pakistan by extending loans at crucial times to prevent the country from going bankrupt as a quid pro quo for security services and diplomatic support, according to a new report.
According to an article in India Narrative, Saudi financial support to Pakistan is better seen as a strategic retainer than as loans. Riyadh buys security services and diplomatic alignment with money, while Pakistan has used the breathing space to stabilise an economy it has failed to transform.
On November 4, Pakistan’s finance minister confirmed that Saudi Arabia had rolled over, for an unstated period, the $3 billion deposit that matured on October 31. The next day, Turkey’s Parliament ratified the Makkah defence pact linking Riyadh, Islamabad and Ankara. However, the United Arab Emirates (UAE) had taken quite the opposite decision in April and demanded immediate repayment of $3.45 billion, the article points out.
The report highlights that after years of annual rollovers, the UAE called its deposits in. State Bank of Pakistan (SBP) reserves stood at $16.38 billion on March 27 so repayment meant surrendering 21 per cent of them. Unreplaced, it would have cut reserves to about $12.9 billion, below June 2025’s $14.5 billion.
However, Saudi Arabia extended a lifeline to Pakistan by providing a total of $8 billion in two instalments which constitutes as much as 37 per cent of the $21.5 billion reserves of the State Bank of Pakistan.
“The quid pro quo is physical. Pakistani personnel have served in the kingdom since 1967 while in 2026, about 8,000 troops, a fighter squadron and air defence followed. On October 6, amid Houthi attacks, Saudi Arabia, Pakistan and Turkey moved to rapid deployment of agreed forces,” the article observes.
Creditors differ in what they can vary. The IMF sets conditions and lends against assurances that bilateral partners keep renewing, so Saudi, Chinese and, until April, Emirati deposits sit inside the IMF programme. Multilaterals follow mandates and long tenors. China, the largest single creditor, rolls its deposit yearly at roughly 6.1 per cent and refinances loans separately, the article states.
Gulf deposits are the discretionary layer, and discretion cuts both ways. The UAE had committed under the IMF programme to keep its deposits until September 2027, yet recalled them; the Financial Times reported irritation at Pakistan’s Riyadh ties and Iran mediation, which Islamabad called routine.
The cost of repeated dependence is that Pakistan’s public debt rose from PKR 49.3 trillion in June 2022 to 86.7 trillion in June 2026, up 75.9 per cent. Exports slipped from 10.6 per cent of GDP in FY2022 to 10.0 per cent in FY2025, which is lower than the 11.1 per cent in Bangladesh and 19.0 per cent in Sri Lanka, the article added.
–IANS
sps/na